We’re entering another inning of one of the most extraordinary technological races ever seen.
I came to the tech world more than a decade ago, and I’ve seen plenty of crazy things happen since. Over the years, I’ve had to develop my own way of separating the signal from the noise. That is the whole point of The Business Engineer and The AI Supercycle: building a framework that helps me understand what is happening beneath an increasingly overwhelming news cycle.
For me, that means going back to first principles. What does a technology actually make possible? What needs to exist for it to scale? Who finances it, who controls its bottlenecks, and what happens when its consequences reach far beyond the companies developing it?
Those are the questions from which my definition of the AI Supercycle emerged.
The AI Supercycle, as I define it, is the process through which AI reorganises technology, capital, infrastructure, and economic activity—and, in doing so, reshapes the political and geopolitical conditions that govern its own development.
The feedback between those forces is central to my thesis. AI changes the economy. Those economic changes influence politics and the balance of power. Politics and geopolitics then feed back into where AI can develop, who can access it, how it is financed, and how quickly its infrastructure can be built.
That is the original idea I have been developing through The Business Engineer and The AI Supercycle.
The beginnings of this way of thinking became much clearer to me around 2020. The pandemic exposed vulnerabilities in the technological globalisation we had largely taken for granted. Suddenly, access to manufacturing capacity, critical components, and international supply chains looked much more dependent on geography and political relationships.
I started seeing technology spilling over into everything else. The ChatGPT moment subsequently crystallised that realisation and gave it a much greater sense of urgency.
This is why I have never been satisfied with describing AI as another version of the web, cloud, or mobile cycle.
Even when people describe it as those three cycles combined, I think the comparison can still understate what is happening. It keeps us anchored to the recent history of the technology industry, when the consequences I am trying to understand extend into the organisation of the economy itself.
My reasoning starts with a simple chain of dependencies. If AI can perform an expanding range of economically useful work, its development requires computing capacity. That capacity requires chips, energy, land, equipment, and capital. As those requirements grow, they begin to affect industrial investment, public infrastructure, and the allocation of resources. Once they reach that scale, they become political.
The comparisons I find more useful are therefore railways, electrification, and the early semiconductor era: periods in which technological development became inseparable from physical infrastructure, industrial capacity, and state power.
That is the scale of change I am examining when I talk about the AI Supercycle.
I also see the relatively open, US-centred globalisation of the last three decades as an unusual historical setting. It encouraged us to assume that powerful technologies would spread through increasingly integrated markets and supply chains. I think carrying that assumption into the AI era is a mistake.
The current wave of frontier AI has been driven heavily by private laboratories and private capital, but it is developing within an increasingly contested strategic environment. Governments recognised AI’s importance well before ChatGPT—the United States had a national AI research strategy in 2016, and China published its major development plan in 2017. What has changed is how immediate, expensive, and publicly visible the consequences have become.
To navigate this, I follow a few signals closely.
SoftBank, for example, has become one of my compasses for the financial side of the industry. Its role in Stargate helped make OpenAI’s expansion beyond a Microsoft-centred infrastructure arrangement concrete. In January 2025, SoftBank took responsibility for financing the initiative while Microsoft relaxed its exclusivity over new OpenAI computing capacity. That was less than two years ago, although it already feels like another lifetime.
To me, that development captured something important: the ambitions of the frontier laboratories were drawing in a much wider coalition of capital and infrastructure providers. The next stage of AI would depend increasingly on their ability to coordinate that coalition.
But the biggest mistake we can make today is to assume that the politics of this cycle will consolidate around a single ideology.
One of the implications of my definition of the AI Supercycle is that AI inevitably becomes an issue across political parties, because its consequences reach across society.
This week’s midterms brought that into focus. Ballotpedia reports that voters favoured limits on data-centre development in 40 of the 41 local ballot measures decided on 3 November. Those votes covered different kinds of restrictions and conditions, but together they show how contentious the physical footprint of AI has become in the communities being asked to accommodate it.
The concern was already crossing party lines. In September, the House passed the Ratepayer Protection Act by 417 votes to three. The bill would require state utility commissions to consider standards making large data centres cover the additional infrastructure costs they create.
A politician is, among other things, a barometer of the pressures felt by their community. When those pressures show up through electricity bills, water supplies, construction projects, or concerns about employment, politicians across the spectrum have an incentive to respond.
Anthropic is another reason I resist reading this through a simple left-versus-right lens.
Its disagreements with the Trump administration over safeguards have coexisted with a hard line on Chinese access to advanced AI. In March 2025, it explicitly advocated tighter semiconductor export controls while calling for an additional 50 gigawatts of dedicated US power by 2027 and faster permitting. Those positions sit together within the same company’s policy agenda.
My reading is that stronger demands for safeguards can coexist with a more determined effort to preserve American AI leadership. Democratic electoral gains could bring tougher conditions for individual projects while leaving the strategic case for domestic capacity intact—or strengthening it.
The eventual pace of construction depends on how those competing pressures are resolved.
The Trump administration has given the buildout political backing through major investment announcements and an explicit AI strategy. Its July 2025 AI Action Plan called for faster permitting, expanded domestic infrastructure, and the export of American AI systems. The next test is how that ambition translates into arrangements that communities, utilities, and state governments are willing to accept.
We also need to pay attention to timing.
SemiAnalysis estimates that roughly three-quarters of the capacity scheduled for 2027 across the top 20 states in its model is already under construction. Most of its projected US additions for 2028 have yet to start. That makes the later pipeline more exposed to changing approvals and development conditions, although projects already underway can still depend on outstanding permits for power or subsequent phases.
This is why I keep returning to the underlying dependencies. Announcing a project, securing financing, starting construction, and delivering usable capacity are different achievements. Each requires a different set of conditions to hold.
Meanwhile, enterprise demand—the economic foundation of the cycle—has continued to expand.
Menlo Ventures estimates that enterprise AI deployment spending reached an annualised rate of approximately $177 billion by September 2026, 5.4 times its comparable estimate a year earlier. Anthropic’s latest filing offers another concrete indicator: approximately $17 billion in third-quarter revenue, compared with $1.4 billion in the same quarter last year.
That supports my view that the industry is still responding to substantial growth in demand. It also requires us to keep asking what kind of demand is growing, how much customers will pay for it, and whether the resulting revenue can support the infrastructure commitments being made.
Ramp’s latest token data illustrates the distinction: among the customers it tracks, usage grew much faster than expenditure. Falling prices and improving efficiency can expand adoption while changing the economics of the capacity built to serve it.
For me, this is the AI Supercycle unfolding in practice. The technology is becoming entangled with debt, financing, energy, national strategy, and local permission. Each of those forces now feeds back into the industry’s ability to keep expanding.
That is precisely why I developed the framework around the interaction between technology, macroeconomics, and geopolitics. As AI becomes more consequential, understanding the technology alone explains a smaller part of what determines its trajectory.
My compass still points towards execution as the central immediate risk: the ability to finance, permit, power, and build the capacity that expanding adoption requires.
Demand is growing. The question I am watching is whether the industry can translate that demand into infrastructure that can actually be delivered—and generate the durable revenue needed to sustain it.
This was the week the AI Supercycle met the ballot box. The vote did not answer in the language of a ban. It answered in the language of permission: who may build, on whose grid, and who pays for it.
It started with numbers. Anthropic’s amended S-1 put a $17.0 billion quarter and $895 billion of compute commitments in front of every investor at once. Apple, Palantir and AMD reported. Then the United States voted, and the industry learned in one night that its next two years of building need consent it had assumed.
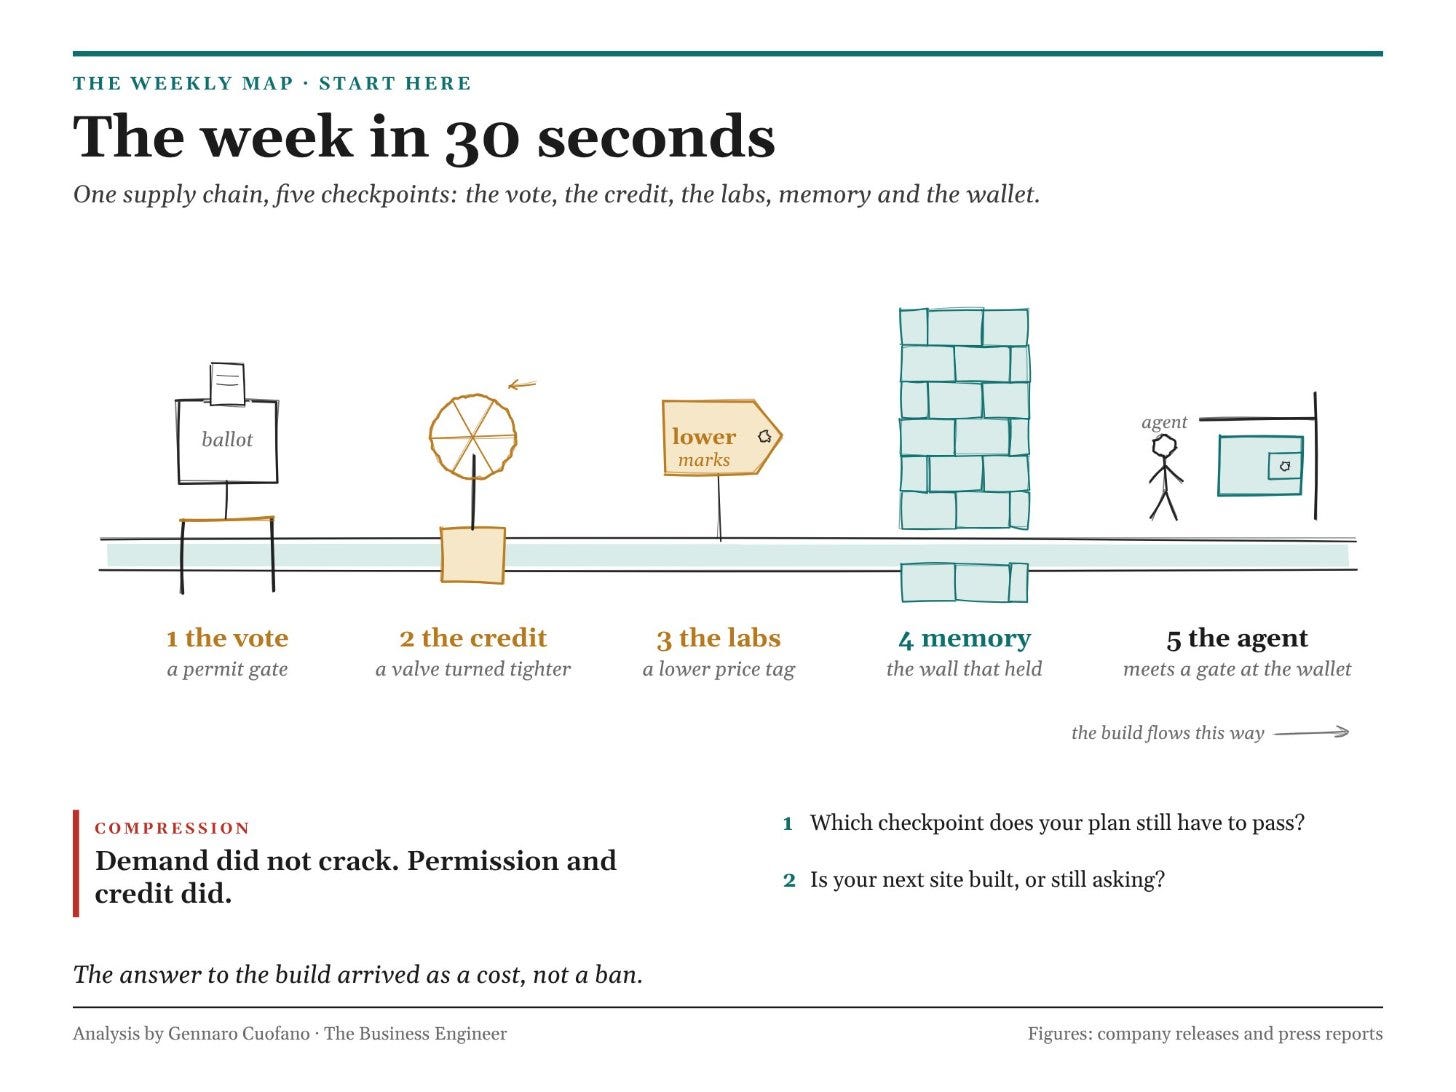
Think of the AI build-out as one long supply chain again. Last week the builders opened their books and the build-out got a credit rating. This week voters, lenders and public-market investors opened theirs, and the answer came in five parts.
The vote turned data centers into a permission problem. Of 41 local data-center measures on the ballot, 40 went the way of limiting development, Ballotpedia’s count shows. New governors who back a pause now sit over states holding about 41% of planned US data-center capacity, on Cleanview’s tracker. The pressure on the build crossed party lines, and so did the answer: make the builders pay their own way.
The rout went global, then into credit. Twelve AI stocks closed $1.45 trillion lower on Thursday as Nvidia fell 9.3%. On Friday Korea’s KOSPI was halted after an 8.6% plunge and TSMC opened limit-down. SoftBank’s dollar bond had its worst day in ten weeks, and the cost to insure SpaceX’s debt hit a record 286.56 basis points.
The private marks met the public price. Prospective investors discussed an Anthropic IPO value of $1.2 trillion to $1.3 trillion, down from $1.5 trillion to $1.6 trillion earlier in the week, Bloomberg reported. OpenAI closed about $11 billion at $1.25 trillion.
Memory stayed the wall. Global DRAM revenue rose 369% to nearly $200 billion on about 4% more bits, Counterpoint said. HBM prices are seen up 121% in 2027.
Agents moved into the money, and met gates. Claude launched personal finance through Plaid, read-only. Visa found shopping agents failed 42.8% of its test runs and often bought something anyway.
The short version: demand for compute did not crack this week. Permission and credit did. On rout day, nine of the ten AI names that reported beat their estimates, and four of them still fell.
The week in one line. For two years the AI build-out was priced as a supply story, and last week as a credit story. This week it was priced as a permission story, and the answer arrived as a cost, not a ban.
How to read this issue
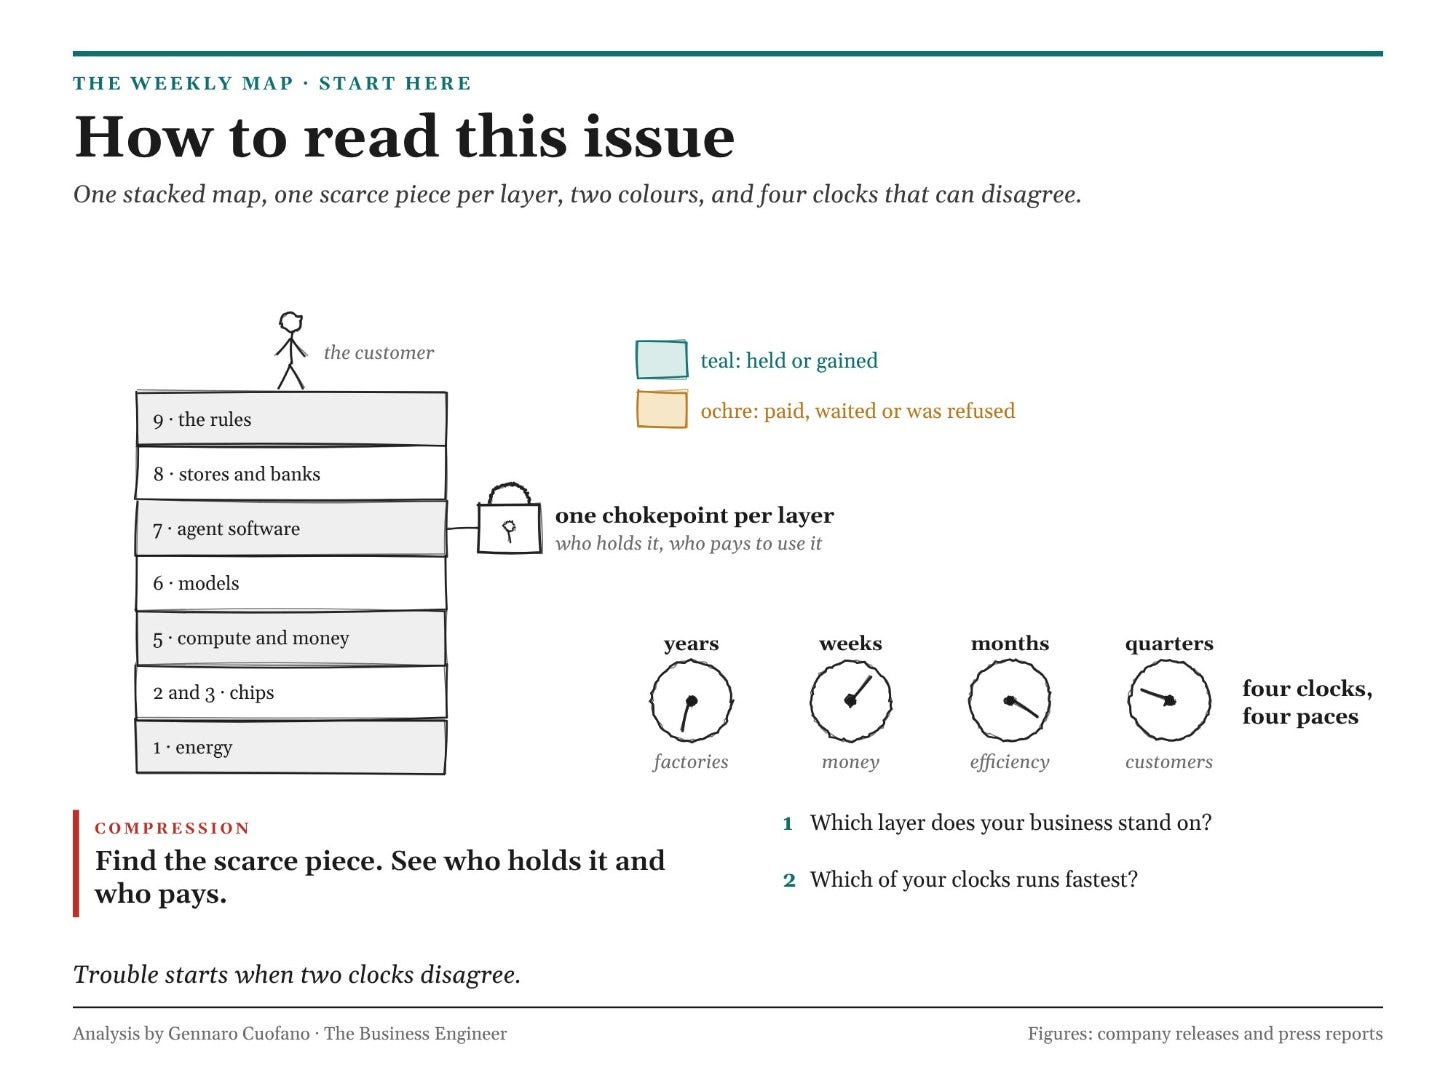
Every week we read the news onto one picture, the Map of AI. It stacks the industry in layers, from energy at the bottom to the rules at the top. Here are the five ideas the rest of the issue uses.
The Map of AI

Seven weeks since the March 13 map. The five-race frame held. What changed is the velocity inside the frame — and in the last fourteen days, the velocity broke into a new register.
The layers. Energy is Layer 1, and chips and their parts are Layers 2 and 3. Compute and the money that pays for it are Layer 5, models are Layer 6, and the agent software around them is Layer 7. The stores and banks agents must pass are Layer 8, and the rules are Layer 9. The paying customer sits above the map as Adoption.
The chokepoint. Each layer has one scarce piece this week. For each, we name who holds it and who pays to use it.
The colours. In the pictures, teal marks the side that held or gained. Ochre marks the side that paid, waited or was refused.
The cascade and the loop. World politics shapes the economy, and the economy shapes technology. In a supercycle the arrows also run back: AI moves the economy and politics in return.
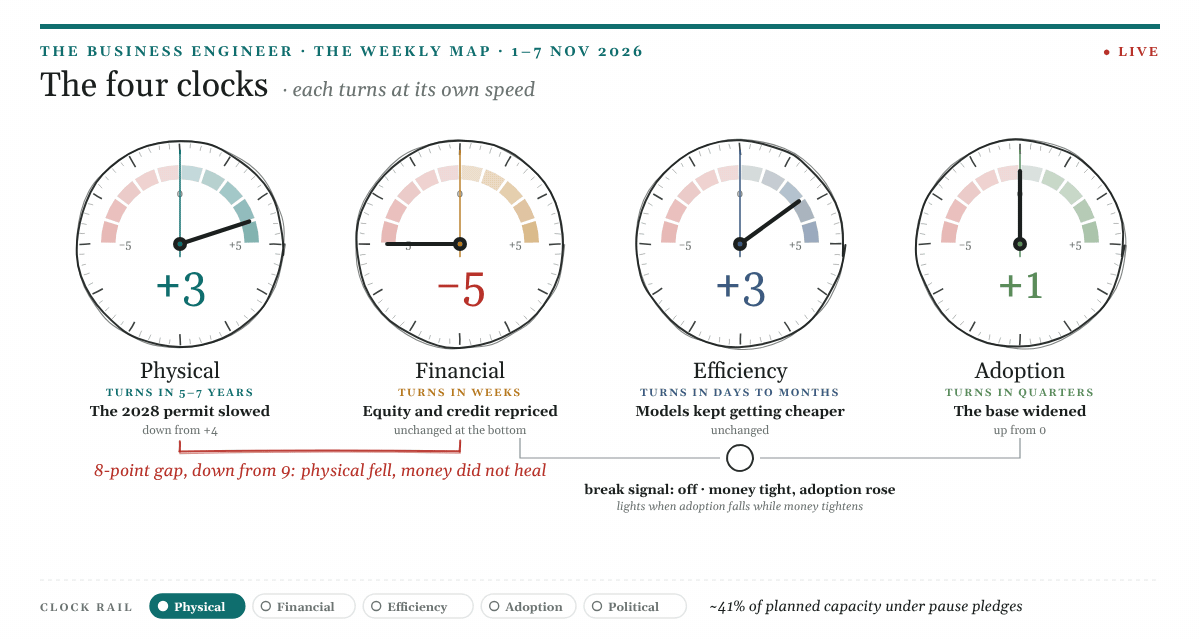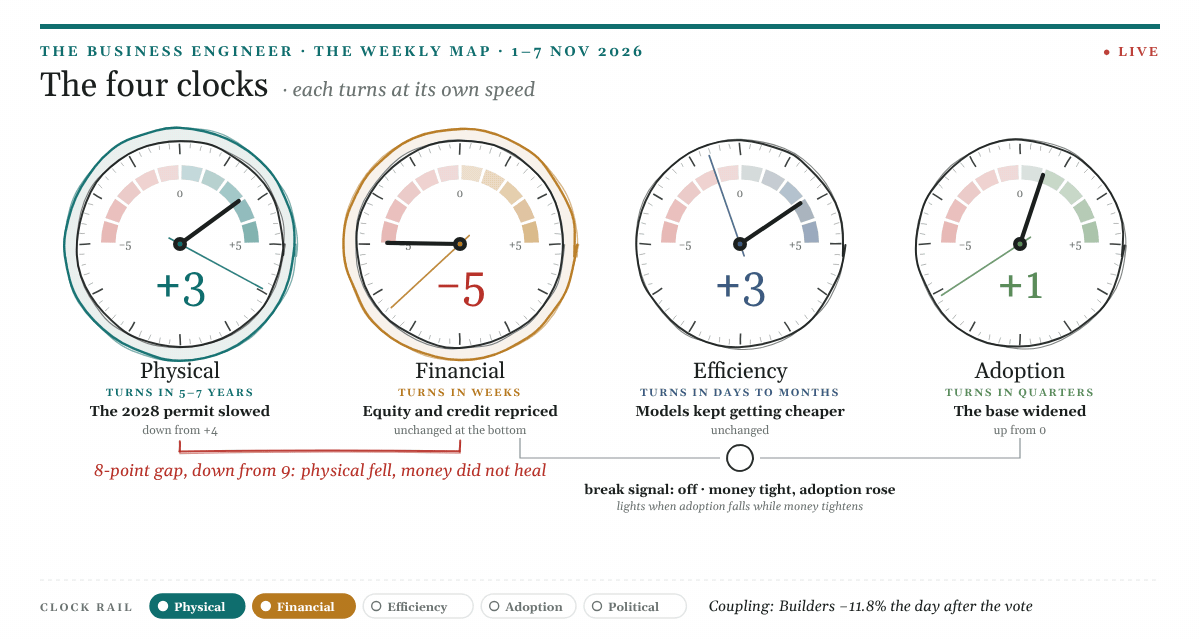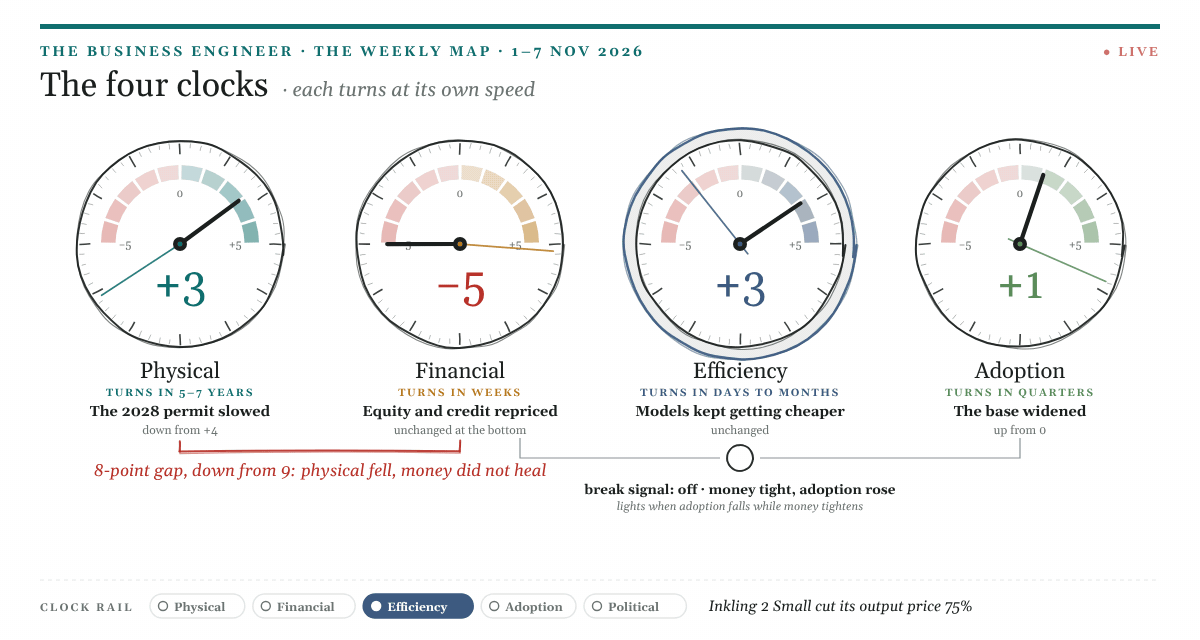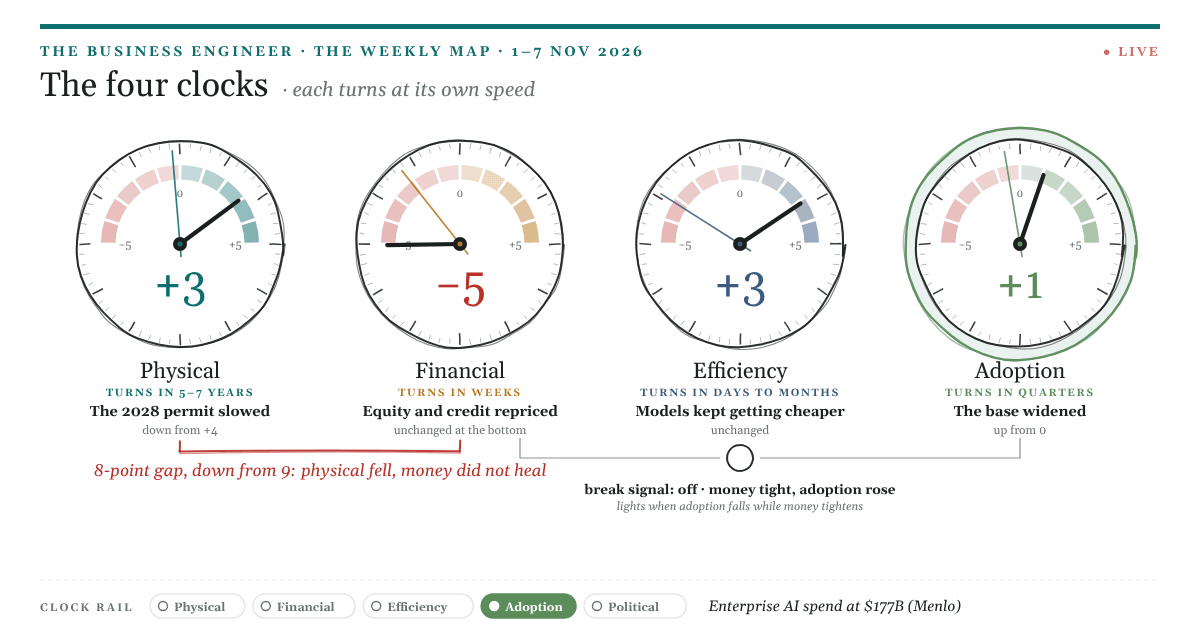
The four clocks. Each part of the build runs on its own clock: factories over years, money over weeks, efficiency over months, customers over quarters. Trouble starts when two clocks disagree.
Two habits to note. “Reported” marks figures from news outlets that the companies have not confirmed. “By our arithmetic” marks a sum or ratio we worked out from published figures.
One more for this week. When we write about the election, we describe what each outcome changes for the build: permits, power, timing and cost. We do not score the candidates or the parties. The data-center question cut across party lines, and the piece treats it that way.
Demand Held. Permission and Credit Repriced.
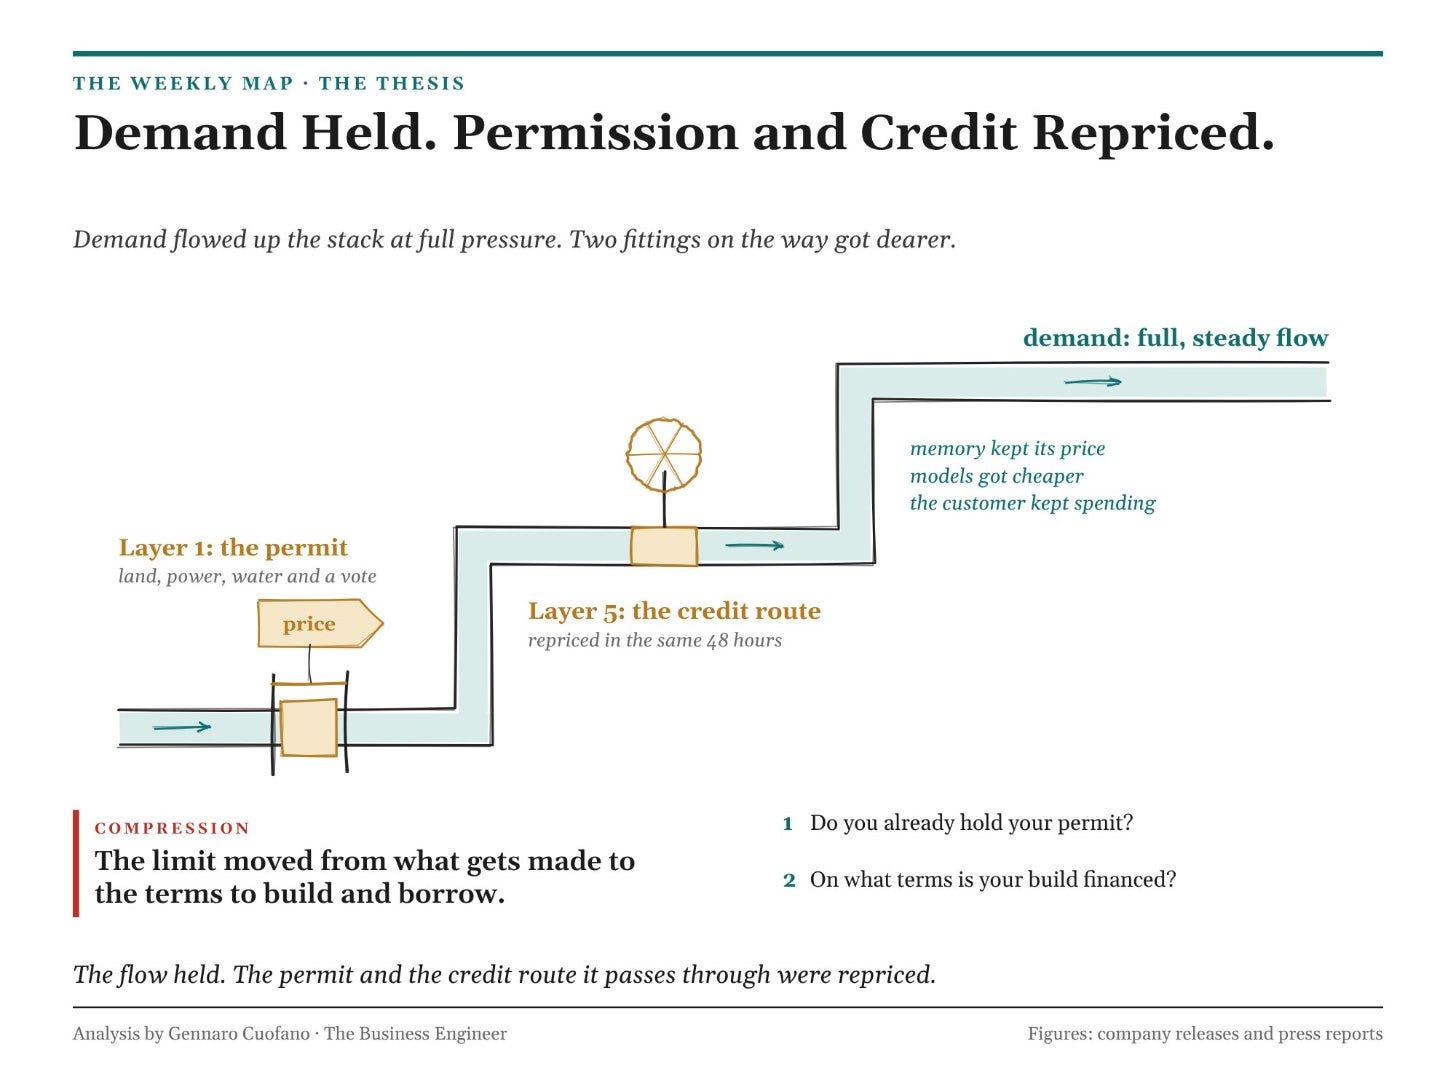
Start at the bottom of the map and climb. Every layer had a side that gained and a side that paid this week. The pressure gathered on two of them.
The first was the permit, in Layer 1. A data center needs land, power, water and a vote it can no longer assume. The second was the credit route, in Layer 5, where the money that pays for the build was repriced in the same 48 hours, from Seoul to New York.
Between those two pressure points, the rest of the stack behaved as it has for months. Memory kept its price. Models got cheaper. Agents moved closer to money. The customer kept spending. That contrast is the week’s real finding: the constraint moved from what the industry can make to the terms on which it is allowed to build and borrow.
The Body of Knowledge is Part of The Enterprise Embedding Series!

From Who Rates the Build to Who Permits the Build
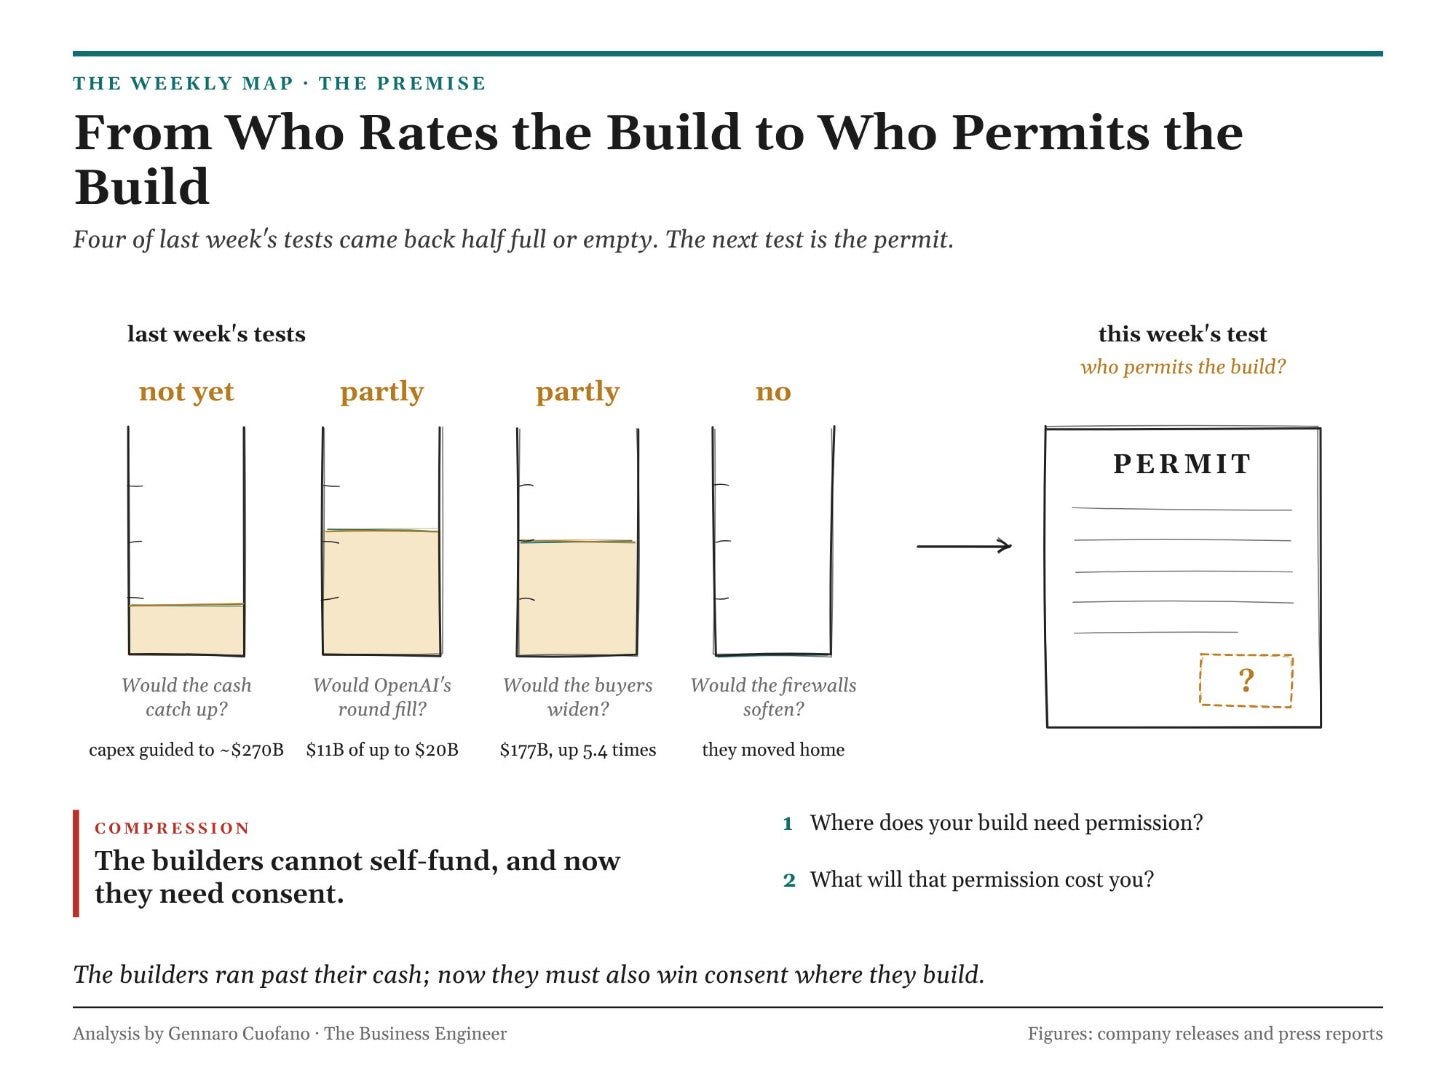
Last week’s issue asked who rates the build. The answer was that the builders had run past their own cash and that the credit market had started to price it. That issue closed with tests for this week. Four came back.
Would the cash catch up? Not yet. Big Tech and SpaceX guided fourth-quarter capex up to about $270 billion, above the third quarter. The off-book bills of the biggest builders now top four years of their cash flow. The gap widened before it narrowed.
Would OpenAI’s round fill? Partly, and at the old price. It closed about $11 billion at a $1.25 trillion valuation, the first tranche of a round that could reach $20 billion, Bloomberg reported. SoftBank, its largest backer, was said to be weighing less than $1 billion more.
Would the buyers widen? Partly. Enterprise AI spend reached $177 billion, up 5.4 times in a year, on Menlo Ventures’ survey. But OpenAI and Anthropic are set to buy about 30% of the world’s new compute in 2027, SemiAnalysis’s Dylan Patel estimated. The buyers grew; the biggest grew faster.
Would the firewalls soften? No. They moved home. Last week’s fences were drawn by states against other states. This week voters drew them around their own towns.
So this week’s question follows from last week’s answer. The builders cannot fund the build from operations alone, and now they need consent where they build. Where does the build need permission, and what will the permission cost?
The Midterms, Read Through the Build
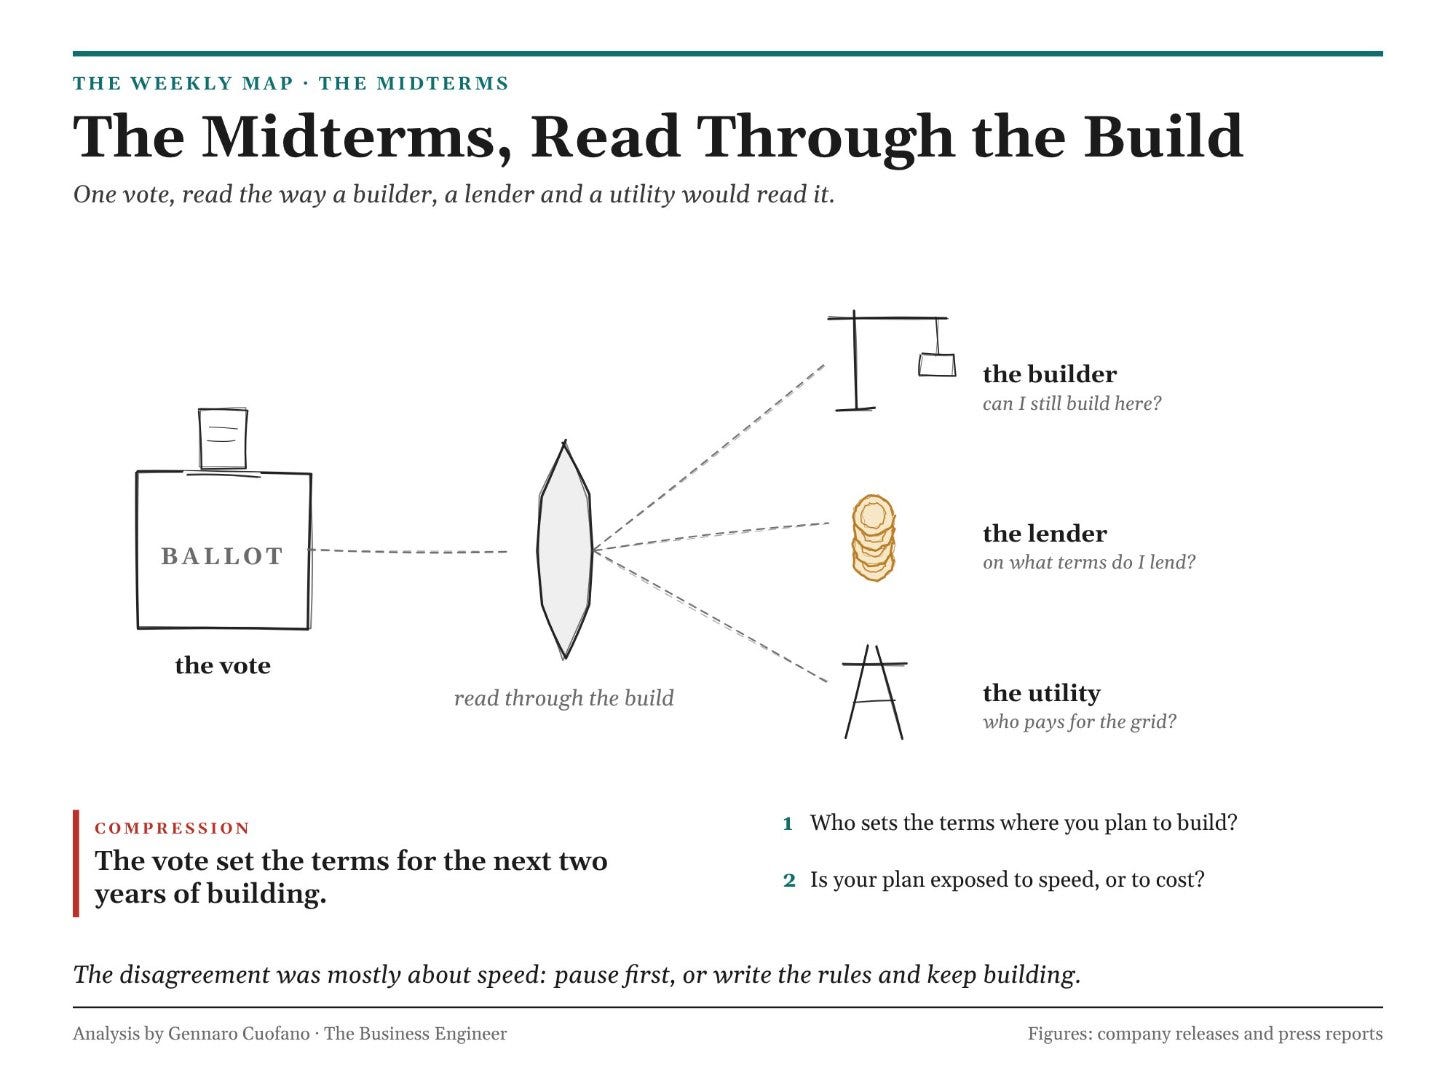
The 3 November midterms were not about AI. Affordability, the war with Iran and the president’s approval drove most of the result. But data centers were on more ballots than ever, and the outcome changes who sets the terms for the next two years of building. This section reads the vote the way a builder, a lender or a utility would: what changed, where the power to act sits, and what it means for capacity due in 2027 and 2028.
It does not take a side. Both parties’ voters said they do not want a data center next door, by different margins. Both parties’ candidates proposed making builders pay their own grid costs. The disagreement was mostly about speed: pause first and write the rules, or write the rules and keep building.